
Freelancing offers individuals the freedom and flexibility that are often appealing. However, this career path comes with its challenges that can dim the initial allure, especially when compared to the stability of traditional full-time employment.
The necessity of juggling financial responsibilities is arguably the biggest sticking point every freelancer must face. Rather than letting it overwhelm you, take note of the following tips, and you’ll soon find yourself as the master of your money rather than subjugated by it.
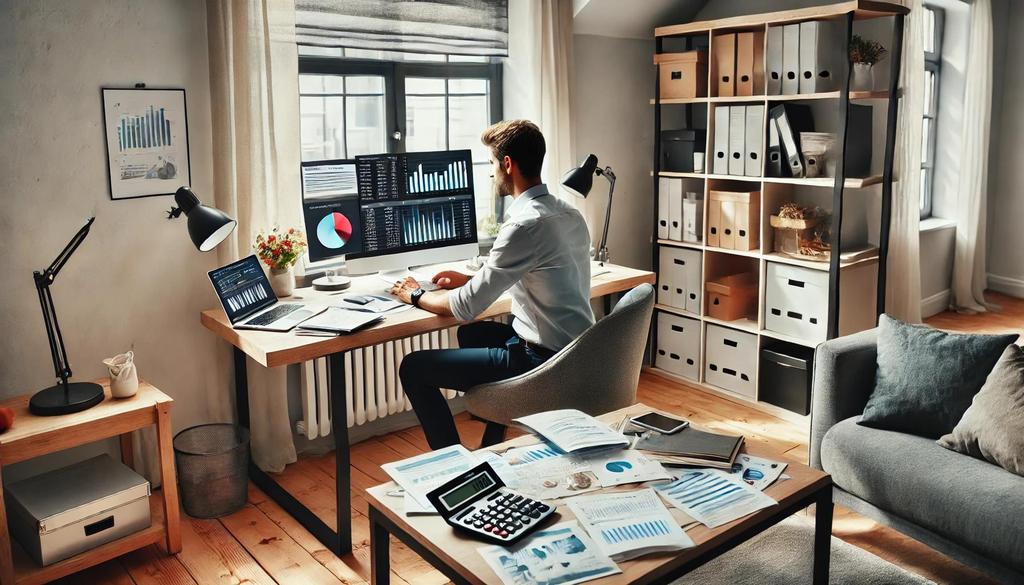
Using Financial Software to Simplify Expense Tracking
To say that keeping track of every penny can cause headaches for freelancers is the understatement of the century. Given that self-employed people pumped $1.27 trillion into the economy last year, that’s a lot of cash to corral. Financial software steps in here, making life easier.
Consider these tools:
- QuickBooks: This robust tool handles everything from invoicing to tracking expenses and managing payroll.
- FreshBooks: It’s user-friendly with time-tracking features, ideal for freelancers juggling multiple projects.
- Wave: Free accounting software perfect for small businesses, offering invoicing and receipt scanning.
Each option helps categorize expenses automatically. So, instead of sifting through endless receipts, you simply review monthly reports. Automation also means fewer errors and a clearer financial picture. These tools sync with your bank accounts too. Integration ensures all transactions are logged accurately without manual inputs involved. You can even factor these tools in as part of your effective invoicing practices, so it’s an all-round good idea to adopt accounting software as a priority.
Optimizing Your Home Office Deductions
Among the must-know tax deductions for freelancers, home office costs are at the top of the list. These deductions can save you a substantial amount on your taxes if you use a part of your home exclusively for work.
Here’s how to maximize those savings:
- Dedicate a Workspace: Ensure that an area in your home is used solely for business purposes. This could be an entire room or even just a designated space. Taking the lead from modern workspaces is sensible to maximize its productivity and comfort potential.
- Calculate Correctly: Measure your workspace’s square footage, then divide by your home’s total square footage. This percentage applies to various expenses like rent or mortgage interest.
- Include Utilities and Repairs: Deduct portions of utilities (electricity, internet) and repair costs that pertain to the whole house but support your office space.
Also, track everything meticulously:
- Keep receipts for all purchases related to maintaining and furnishing your office.
- Log monthly utility bills highlighting the business-use portion.
The tools we talked about earlier can help with all this, so there’s no need to miss out on potentially sizable savings if you’re an entirely remote freelance hero.

Setting Up a Dedicated Business Bank Account
Separating personal and business finances is another must-do for freelancers. A dedicated business bank account simplifies bookkeeping and makes tax time less stressful.
Here are the steps involved:
- Choose the Right Account: Look for accounts with low fees, good customer service, and easy online access. Popular choices include Chase Business Complete Banking or BlueVine.
- Direct All Income Here: Deposit all freelance income directly into this account to maintain clear records of earnings.
- Pay Expenses from This Account: Use this account to cover all business-related expenses, making it easier to track deductible costs.
The major benefits of doing this include:
- Unfussy Accounting: As mentioned, keeping transactions separate avoids confusion when reconciling books at month-end.
- Professionalism: Using a business account can enhance your credibility with clients.
- Better Cash Flow Management: Monitor your business’s financial health in real-time without personal expenses muddying the waters.
Finally, don’t forget to regularly review statements, as you want to ensure that only relevant transactions appear on this account. Also be aware of fees and transaction limits which can apply to business accounts, with monthly costs up to $30 depending on the bank chosen.

Budgeting for Income Uncertainties
Freelancers often face irregular income, whether due to spells when work dries up or the fact that 74% of self-employed people don’t get invoices paid before agreed deadlines have passed. Managing these fluctuations is at the core of maintaining financial stability.
Here’s how to create a flexible budget that accommodates this reality:
- Track Your Earnings: Record your income each month. Use tools like Excel or budgeting apps such as YNAB (You Need A Budget).
- Determine Average Monthly Income: Calculate an average from the past 6-12 months to set a baseline for your budget.
- Prioritize Essential Expenses: Identify and prioritize non-negotiable expenses like rent, utilities, and groceries.
With this in hand, it’s time to build a safety net:
- Emergency Fund: Save at least three to six months’ worth of living expenses. This fund cushions against lean periods.
- Variable Expense Planning: Set aside money during high-income months for variable costs (travel, entertainment) when earnings dip.
Also, you need to adopt strategic spending habits:
- Automate Savings: Direct a portion of every paycheck into savings automatically.
- Limit Fixed Costs: Minimize recurring monthly obligations to keep overall expenditures flexible.
Last of all, make sure to monitor cash flow regularly and review your budget monthly so you can adjust it based on actual income rather than just relying on your projections.

Tools and Strategies for Financial Stability as a Freelancer
Accounting software, a proactive approach to deductibles, a dedicated business bank account, and a resilient budget that’s set up for good times and bad will all contribute to a less stressful and more sustainable freelance career.
That said, you should still aim to outsource some or all of this to a certified accountant at some point down the line since a pro will know what’s best for your needs, and the price you’ll pay for their services will more than cover itself in terms of tax savings and peace of mind.


