
What happens when an aging parent starts needing more help than the family can comfortably afford? It rarely happens overnight. A few extra prescriptions, occasional home assistance, and more frequent medical appointments gradually become permanent expenses.
Then there’s the question of long-term care and, eventually, end-of-life arrangements.
It’s a lot to take in, especially when everyone has other financial responsibilities. The good news? Families can prepare for many of these costs before they become overwhelming.
The Costs of Aging Go Far Beyond Medical Bills
Healthcare costs tend to dominate conversations about aging.
Yet medical care is only one piece of the puzzle. As people get older, expenses related to housing, transportation, and everyday support services can become just as significant.
According to the 2025 CareScout Cost of Care Survey, assisted living now runs a national median of $6,200 per month. A private nursing home room reaches a median of $129,575 a year, and non-medical in-home caregiver services run $35 per hour at the median.
Taken together, those costs show why retirement planning often requires a bigger financial cushion than people expect.
The Expenses That Don’t Always Make the Retirement Budget
Imagine your father has lived independently for decades, but climbing the stairs is becoming difficult. Suddenly, the family is discussing bathroom modifications, grocery deliveries, and someone to help with cleaning.
None of these expenses seems extraordinary on its own. Together, however, they can put considerable pressure on a fixed retirement income.
Some of the often-overlooked expenses include:
- Home modifications: Ramps, grab bars, stair lifts, specialized showers, and other accessible features
- Transportation assistance: Arranged rides to medical appointments and errands
- Personal support: Paid assistance with bathing, dressing, cooking, and housework
- Medical equipment: Mobility devices, implants, and other medical supplies
- Caregiver respite: Temporary adult day care and other short-term care options for family members in need of a break
Most families don’t realize these costs are creeping up on them until suddenly they’ve grown into a pretty sizeable monthly total.
Making Aging and End-of-Life Expenses Easier to Manage
Knowing that these expenses are coming is one thing. Figuring out how to pay for them is another. Families don’t need a perfect financial forecast, but they do need a few practical arrangements that can make the years ahead less stressful.
Here are seven ways to get started.
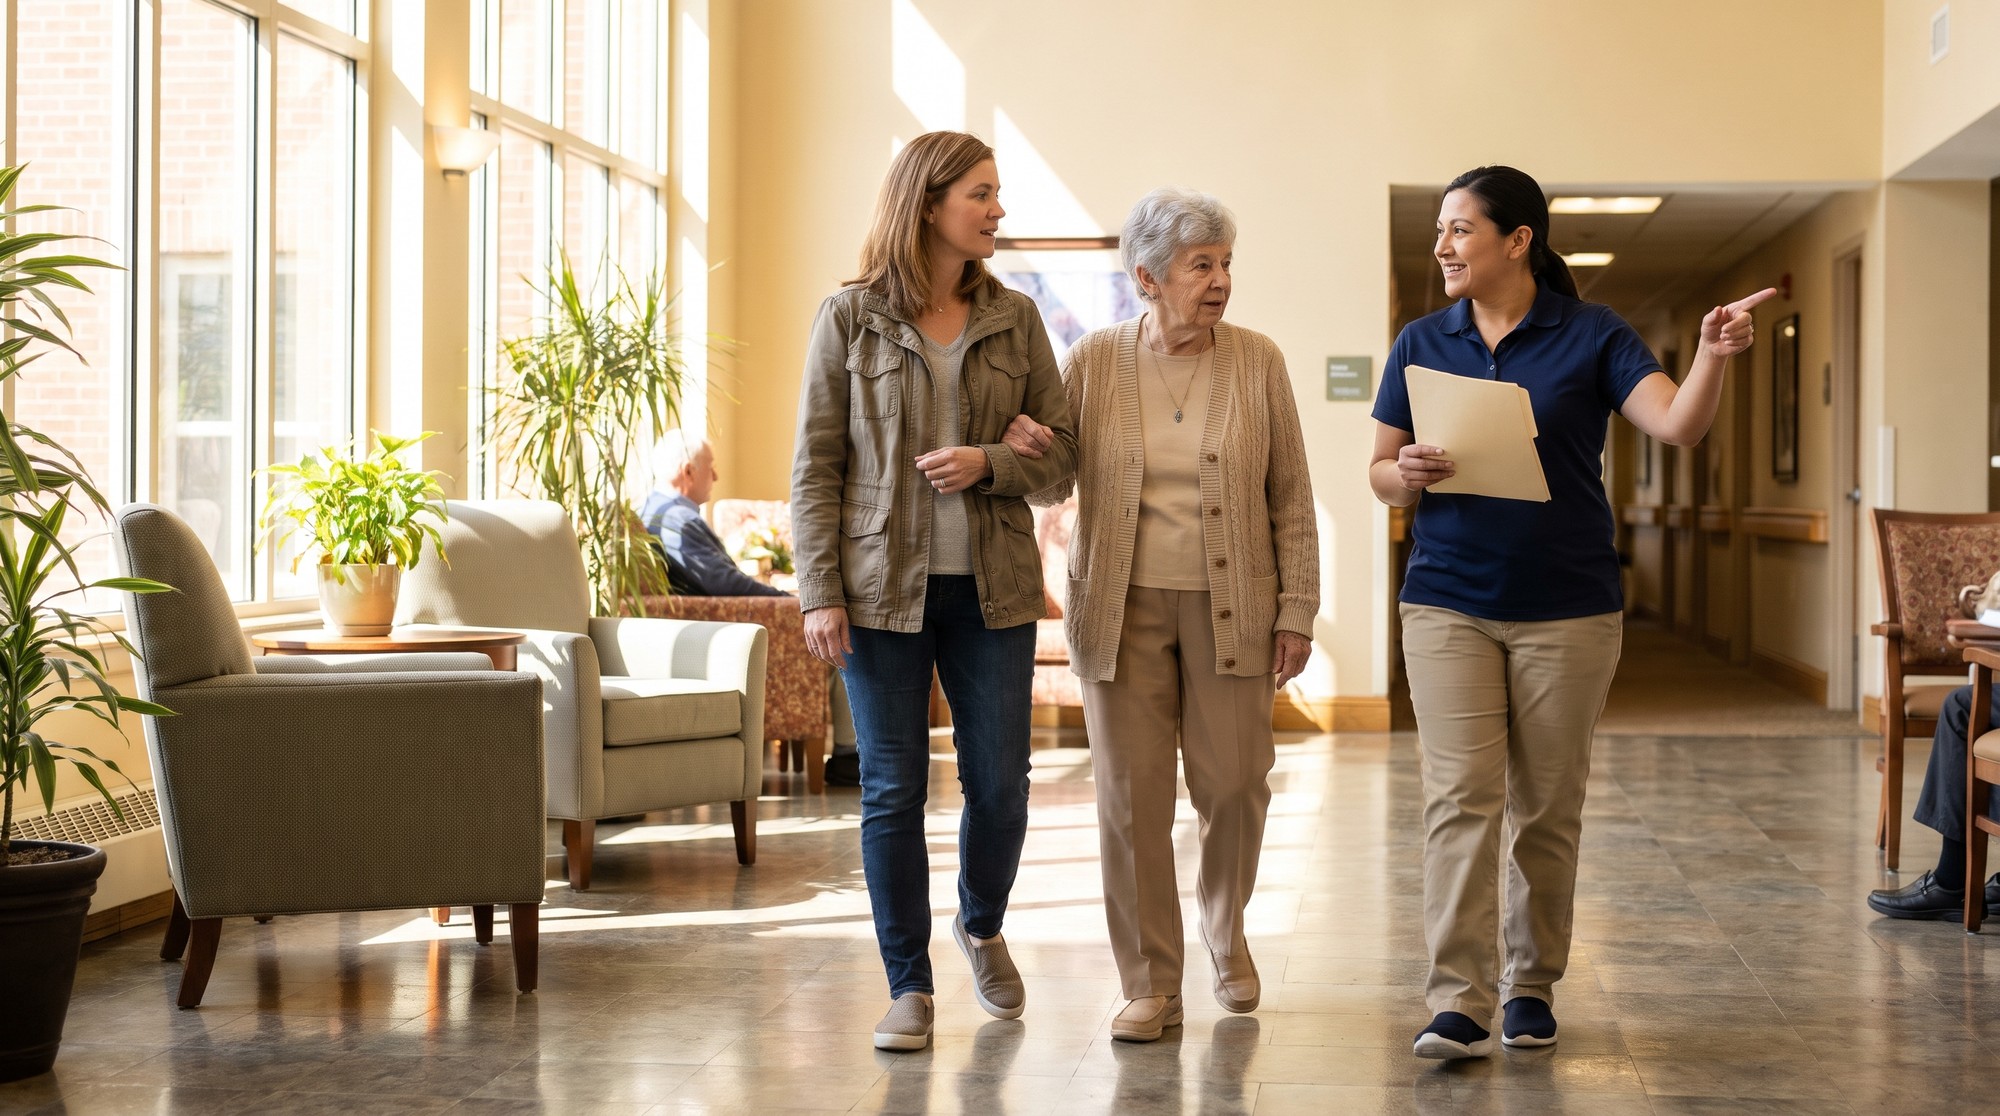
1. Start Estimating Future Care Costs
Don’t wait until you’re in the thick of things before you start researching potential care options for your loved ones.
Research the costs of home caregivers, assisted living facilities, and nursing homes, and ask for estimates from each so you’ll have a ballpark figure of what they may run.
Average costs around the country can provide a baseline, but they’ll vary between states and providers. Find out what’s included in the services because some facilities charge extra for specialized care, medication management, and higher levels of assistance.
2. Create a Dedicated Aging-Care Savings Fund
Having a dedicated savings account for future elder care can give your family a little financial breathing room. Even making small, frequent deposits can eventually add up to a decent storehouse for everything from home renovation costs to temporary care and unexpected bills.
When multiple children are involved, consider discussing the idea openly and coming to an agreement about who will contribute the most financially and who will handle paperwork, appointments, and other responsibilities.
3. Make Room for Funeral and Final Expenses
Funeral costs are easy to overlook until families are suddenly forced to face them.
The National Funeral Directors Association reports that a funeral with viewing and burial ran into the mid four figures in its 2023 price survey, while a funeral with viewing and cremation cost noticeably less. Those figures don’t include extras like cemetery plots, headstones, or grave markers.
That’s why many families plan ahead for paying for end-of-life costs rather than leaving loved ones to cover the expense unexpectedly. One option is final expense insurance, a smaller whole life policy that can help cover funeral expenses, medical bills, and other outstanding obligations.
Coverage often ranges from $2,000 to $40,000. Some policies require only a few health questions, while guaranteed-issue plans may not require any medical information at all, making it important to compare costs, waiting periods, and benefits before choosing coverage.
4. Explore Long-Term Care Insurance
Long-term care insurance may be a good choice if you want to supplement your parent or grandparent’s savings with coverage to help offset the high costs of eligible home-based and assisted-living services.
Most policies will cover home-care visits, assisted living or nursing home care, or adult day care programs, with a waiting period for coverage to take effect.
Do your homework ahead of time so you understand the terms of any potential policy, including premiums, benefits, waiting periods, and exclusions.
5. Organize Important Financial and Legal Documents
Imagine trying to hunt down all of a loved one’s insurance policies, savings accounts, and other important documents when they’re admitted to the hospital. Certainly not a relaxed experience.
Talk through and document your loved one’s estate plans, including wills, living trusts, durable powers of attorney, and health care directives, and make sure the documents are kept in a place where everyone can find them if needed.
6. Check Available Government Benefits
Before paying out of pocket for everything, look into what government programs might pay for some or all of your loved one’s costs.
If your loved one has served in the military, see if he or she qualifies for Department of Veterans Affairs programs. These programs have different application rules, so it’s worth checking eligibility before assuming family savings must cover everything.
7. Account for the Family Caregivers
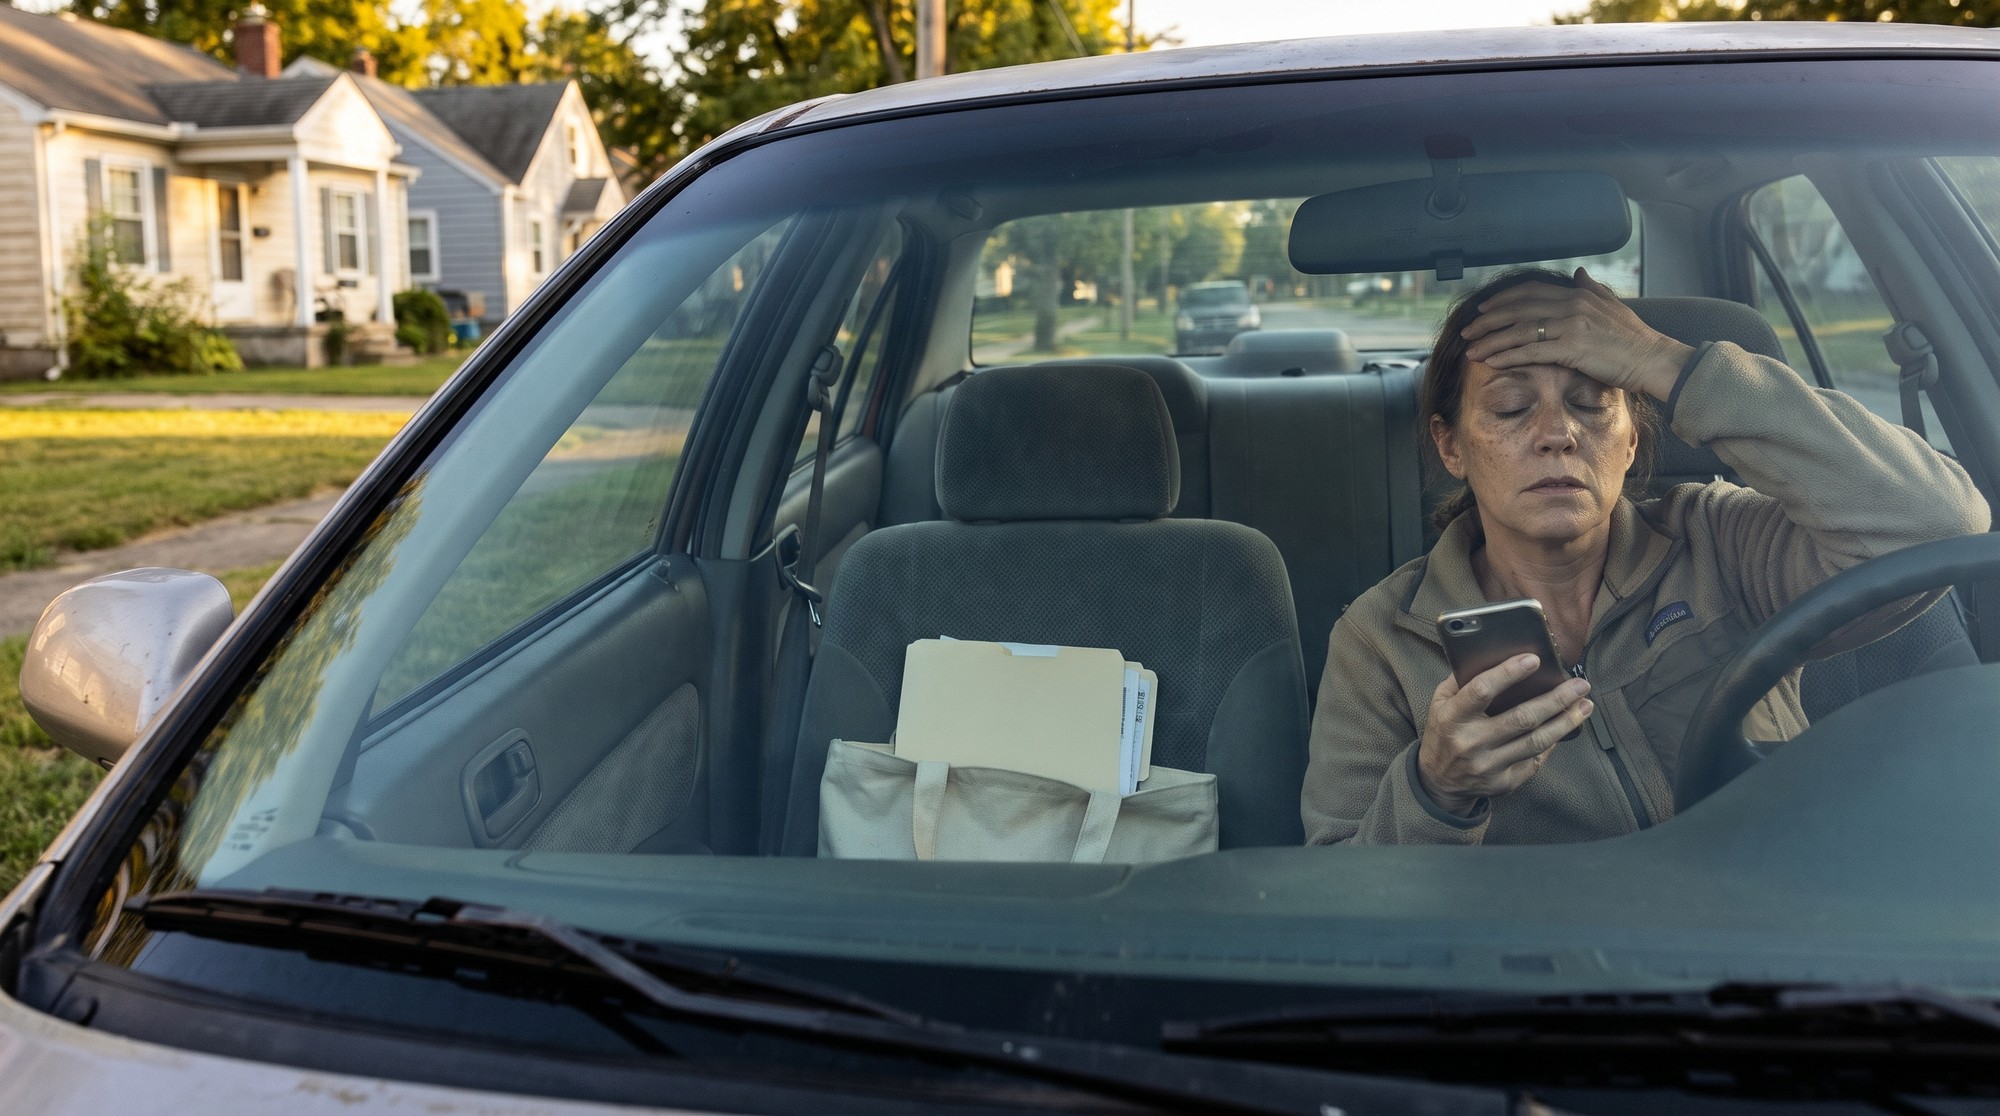
Here’s a number many don’t consider: the indirect cost of family caregivers providing their loved one’s care. An adult child might have to work part-time, turn down a promotion, or spend hours of time between home and their parent’s house traveling back and forth.
Before assuming that one person can manage everything, discuss how tasks will be divided and decide whether there are alternatives, including employment flexibility, respite services, or monetary contributions from other family members who can’t offer physical help.
A Little Preparation Can Change Everything
Aging is complicated enough, without throwing confusing financial decisions into the mix.
Families shouldn’t have to anticipate every incident in an emergency or budget for every cent of their last farewell. They need a practical plan, organized paperwork, and practical insights into what their resources truly support.
Begin with baby steps if needed. One talk, one cushion, one policy. Perhaps the best parting gift you can give your family is not money but time.
Give them the time to spend it instead of looking for it.

