
Saving money on taxes is something that everyone would like to do. You can keep more money in your pockets by taking advantage of a few key strategies. Fortunately, there are a variety of simple yet effective ways to reduce your tax burden. In this article, we will discuss six practical strategies that will help you save money on your taxes.
Take Advantage of Tax Deductions
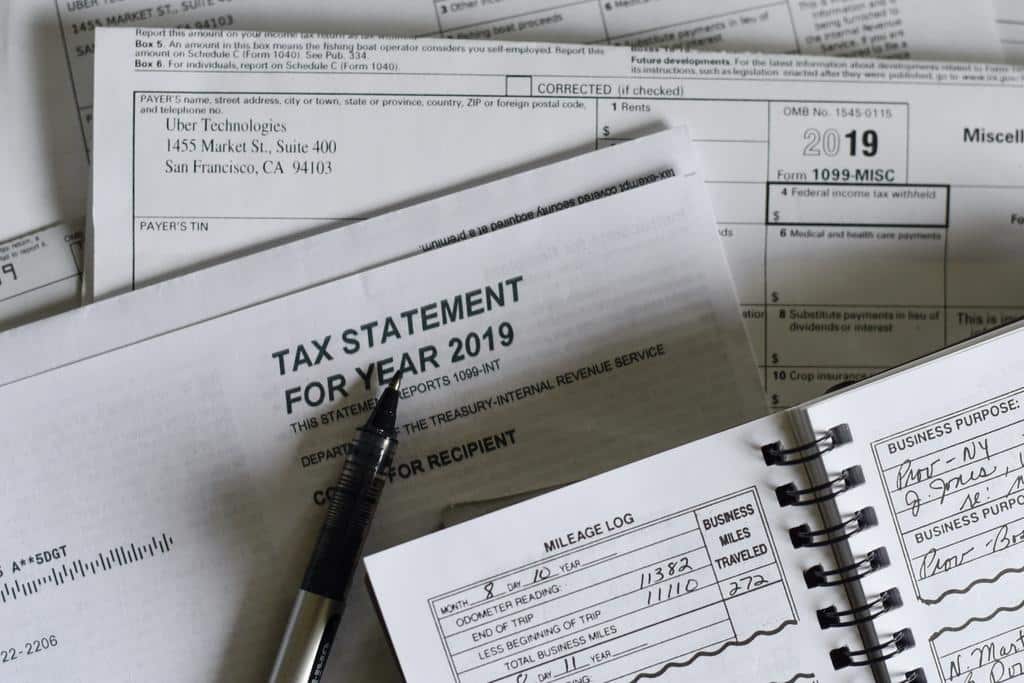
There are ways to reduce the amount you owe by taking advantage of tax deductions. By identifying which deductions you’re eligible for, you can potentially save hundreds or even thousands of dollars on your taxes each year. From charitable donations to home office expenses, plenty of deductions can help lower your tax bill.
Common tax deductions to consider
There are a variety of deductions to consider, and some of the most common deductions include charitable donations, mortgage interest, and medical expenses. It’s essential to understand how these deductions work so that you can maximize your savings and minimize your tax liability.
Advantages
- Reduced Tax Liability: Claiming deductions reduces taxable income, lowering your tax owed and leading to substantial savings.
- Increased Tax Savings: Deductions directly reduce taxable income, resulting in significant savings based on your tax bracket. More deductions mean greater potential savings.
- Maximizing Savings: Identifying and using deductions ensures you capture all potential savings, optimizing eligible expenses when filing taxes.
- Encouraging Financial Behavior: Some deductions incentivize beneficial actions, such as charitable donations that support nonprofits and promote philanthropy.
- Flexible Deduction Options: A wide range of deductions allows flexibility to choose based on your financial situation and priorities, maximizing overall tax savings.
- Potential for Higher Refunds: Utilizing deductions raises the chance of receiving a tax refund, as they lower taxable income and may transform a tax liability into a refund.
Utilize Tax Credits
In addition to deducting expenses, utilizing tax credits is another excellent way to save money on your taxes. Tax credits are even more beneficial because they reduce your tax liability after deducting expenses. By taking advantage of tax credits, such as the earned income tax credit, child tax credit, and education credits, you can potentially maximize your savings.
It’s important to have proper documentation, including detailed income information, to ensure accurate reporting and eligibility for these tax credits. One useful tool that can assist you in this process is a paystub generator. With a paystub generator, you can generate professional paystubs that provide a comprehensive breakdown of your income, including earnings, deductions, and taxes withheld.
This documentation not only helps you meet the criteria for tax credits but also serves as proof of income when needed. By incorporating a paystub generator into your tax planning, you can streamline the process, ensure accuracy, and effectively utilize tax credits to reduce your tax liability. Remember to review the specific requirements for each tax credit to ensure you meet the criteria and maximize your potential savings.
Advantages
The advantages of utilizing tax credits include reducing your overall tax liability, increasing your refund, and even potentially boosting your business’s bottom line. By taking advantage of tax credits related to your industry, making energy-efficient upgrades, or even hiring certain employees, you can decrease your tax bill and keep more of your hard-earned money.
Popular tax credits available:
- Child tax credit
- Earned income tax credit
- Education-related tax credits

Contribute to Retirement Accounts
Taxpayers are always searching for ways to decrease taxable income and increase refunds. A common recommendation from experts is to contribute more money to retirement accounts. This approach can be especially beneficial for individuals who are approaching retirement age. Beyond the potential tax benefits, retirement savings can help secure a comfortable future by providing a source of income when working is no longer an option.
Tax advantages of contributing to retirement accounts
One of the most advantageous methods is contributing to retirement accounts, such as a 401(k) or IRA. Doing so reduces your taxable income for the year and saves for your future. Additionally, some retirement accounts offer matching contributions from employers, which can further increase your savings potential.

Plan and Time Your Income
Another practical strategy to consider is planning and timing your income. By doing so, you can take advantage of deductions and credits while minimizing your taxable income. This involves reviewing your income sources and moving them to different periods based on when it would be most beneficial for tax purposes.
Strategies for timing income:
- Deferring income
- Accelerating income
- Considerations for self-employed individuals
Advantages
- Tax Optimization: Planning and timing your income can help you optimize your tax situation. By strategically managing when you receive income, you can potentially reduce your taxable income, which may result in lower tax liability and increased savings.
- Income Smoothing: Planning your income allows for a smoother distribution of earnings over time. By avoiding spikes in income, you can potentially prevent being pushed into higher tax brackets, ensuring a more consistent and manageable tax burden.
- Capitalizing on Tax Brackets: Understanding the tax brackets and their corresponding tax rates enables you to time your income to stay within lower tax brackets. This can lead to significant tax savings by paying a lower percentage of taxes on your income.
- Managing Deduction Eligibility: Timing your income can also help you maximize your eligibility for deductions. By aligning your income with deductible expenses, you can potentially optimize your deductions and reduce your overall tax liability.
- Optimizing Tax Credits: Certain tax credits are income-dependent, meaning they phase out or increase based on your income level. By planning your income, you can potentially qualify for and maximize these tax credits, increasing your potential tax savings.
- Minimizing AMT Impact: For individuals subject to the Alternative Minimum Tax (AMT), planning and timing your income can help you minimize its impact. You can potentially reduce or avoid triggering the AMT by strategically managing income sources, exemptions, and deductions.
Seek Professional Guidance
By working with a knowledgeable tax professional, individuals can ensure that they are taking advantage of all possible deductions and credits and potentially save themselves money in the long run. By consulting with a tax professional, you can take advantage of their expertise and experience to ensure that you are claiming all eligible deductions and credits and that you are not missing any important deadlines.
Advantages
Seeking professional guidance has its advantages and can prove to be a valuable investment in the long run. A tax professional can help identify deductions and credits that may have been missed and help avoid any potential penalties or IRS audits.
Consider Tax Loss Harvesting
While there are many different ways to approach taxes, one strategy that could potentially save money is tax loss harvesting. This involves selling an investment that has experienced a loss to offset taxes owed on gains from other investments. By considering this tactic, individuals can potentially minimize their tax burden and maximize their savings.
Advantages
One of the advantages of considering tax loss harvesting is its ability to minimize taxes while still allowing for investment growth. It’s important to note that tax loss harvesting isn’t a one-time event but rather a continuous process that should be evaluated regularly.
Final Thoughts
Tax laws and regulations can change, so staying up to date and seeking professional advice is crucial. By proactively managing your taxes, you can position yourself for potential savings, increased refunds, and greater financial stability. Take action now and start implementing these strategies to make the most of planning taxes and ultimately save more money in your pocket.

