
If you are like most business owners, you dream of growing your business. Growth signifies a competitive advantage and increased revenue. However, the path to expansion requires capital, and traditional funding methods can be slow. By the time a bank loan is approved weeks or months later, competitors may have already seized market share. Opportunities often vanish without rapid credit availability.
Quick approval of credit lines is a critical tool for business owners who need access to funding efficiently. This article will explore how lines of credit with quick approval can help you accelerate your business growth.
Why Speed Matters in Business Financing
Business is time sensitive; consider a scenario where a 48-hour bulk discount is offered by a supplier, or a perfect office space becomes available with an immediate deposit requirement. While 73% of business lines of credit are eventually approved, most traditional bank applications take weeks to process.
During that delay, three critical things happen:
- The opportunity vanishes as a competitor acts on it.
- Cash flow suffers while operational expenses continue to accumulate.
- Business momentum, which is vital for survival, comes to a halt.
This is why quick credit line approval has become a critical financial tool for strategic business owners.
The Opportunity Cost of Bank Approval Delays
Traditional banks can take up to 90 days to approve a line of credit. In contrast, some online lenders can grant approval in minutes and deposit funds into your account the same day.
The difference in approval time represents a significant strategic gap:
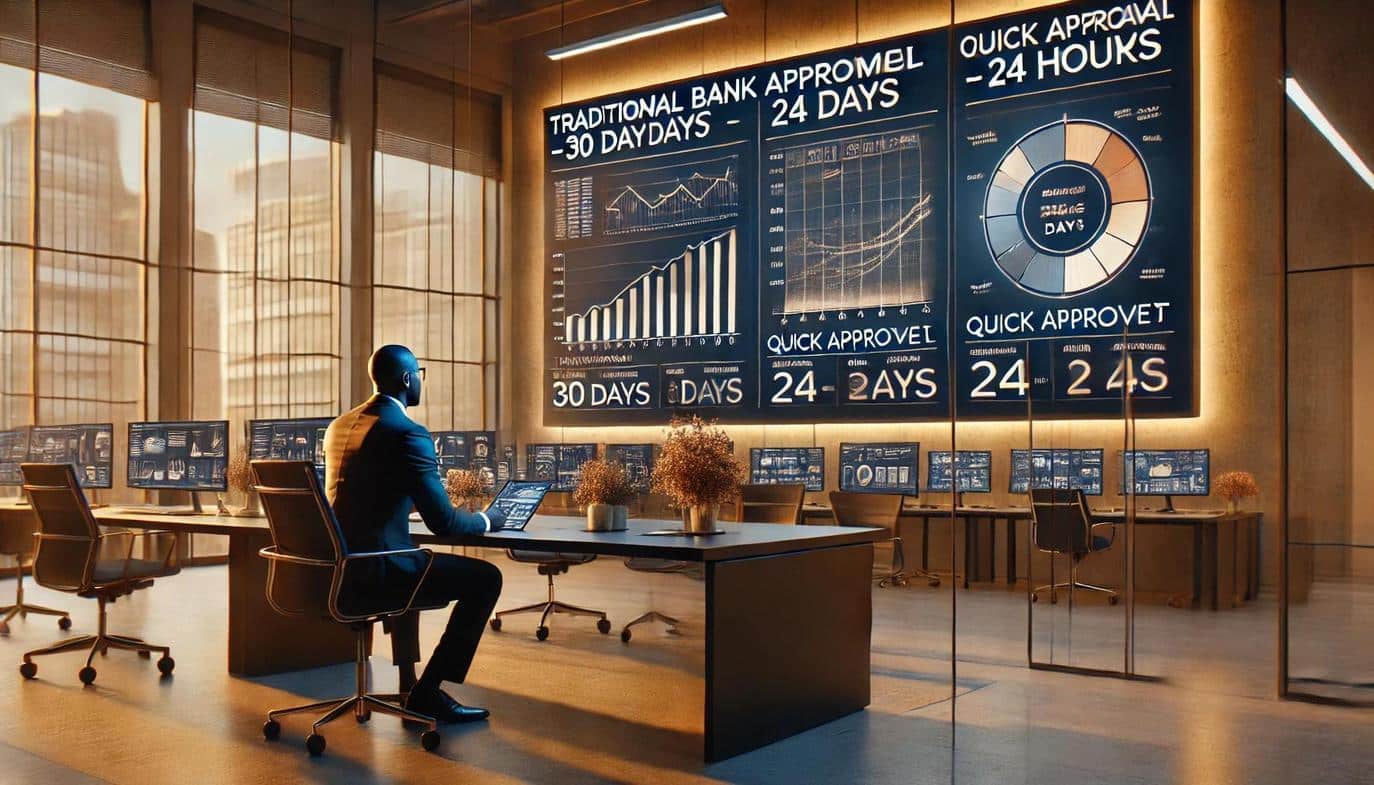
- Traditional Bank: 30 to 90 days for approval
- Quick-Approval Lenders: 3 minutes to 24 hours
This is not merely about convenience; it is about the operational viability of your company. The inability to secure funds quickly can result in losing market share to a more agile competitor.
Driving Business Growth with Quick-Approval Credit Lines
A recent survey indicated that 46% of small business owners could achieve 30-100% growth if they had faster access to operational funding. This suggests that many entrepreneurs have a growth plan ready but are constrained by access to capital.
Quick credit lines enable you to:
1. Seize Time-Sensitive Opportunities
With a quick credit line approval, you can confidently accept time-sensitive offers, such as the 48-hour bulk discount or the ideal office space deposit, without watching opportunities pass by while awaiting a bank’s decision.
2. Manage Cash Flow Effectively
Poor cash flow management can cripple a business more effectively than any competitor. Quick-approval credit lines provide the flexibility to:
- Bridge payroll gaps during slower periods.
- Pay suppliers on time to maintain strong relationships.
- Cover the gap between invoicing and receiving payment.
A key benefit is that you only pay interest on the funds you draw. If you have a $50,000 line available but only use $10,000, you are only charged interest on the $10,000.
3. Scale Successful Marketing Campaigns
If you have identified a high-performing marketing channel, a quick credit line allows you to increase your investment immediately. You do not have to wait months for traditional funding; you can scale your profitable campaigns while they are still effective. Timing is a critical factor in marketing, and rapid credit provides a significant competitive edge.
The Data-Backed Impact of Fast Funding
While 90% of large banks claim they can approve a small loan within 10 business days, the reality is often different. In contrast, some quick-approval lenders can provide funds within 24 hours or less. The disparity between a few hours and ten business days is substantial when opportunities are on the line.
The Growth Connection
The statistic highlighting 30-100% potential revenue growth is not arbitrary. There is a direct correlation between fast credit and exponential growth for several reasons:
- Compound Opportunities: Each quick, decisive action can lead to further opportunities.
- Competitive Advantage: You can act while your competitors are forced to wait.
- Momentum Building: Success and agility build upon each other.
What Proactive Business Owners Are Doing
The most strategic entrepreneurs are not waiting for opportunities to arise before seeking funding. They are establishing quick credit lines proactively.
The strategy is to get approved for a line of credit when the business is performing well and financials are strong. That way, when an opportunity emerges, the capital is instantly available.
This strategy functions as a form of business insurance, protecting against missed opportunities rather than operational disasters.

An Overview of Quick Credit Solutions
Not all fast credit solutions are identical. There are several options that strategic business owners utilize:
Unsecured Business Lines of Credit
These lines of credit do not require collateral, and many can be approved in hours instead of weeks. They are ideal for inventory, marketing campaigns, equipment purchases, and general working capital.
Revenue-Based Financing
This type of financing allows lenders to evaluate your monthly revenue instead of relying solely on credit scores. If your business demonstrates consistent sales volume, approval is typically fast.
Invoice Factoring
If you have outstanding invoices from reliable clients, you can get funded against them immediately. Some lenders will fund an invoice within 24 hours of submission.
Making Quick Credit Work for You
To maximize the benefit of a quick-approval credit line, business owners should take the following steps:
Prepare Your Documentation
Although the approval process is fast, you will still need to provide basic business information. Be sure you have the following ready:
- Last three months of bank statements
- Basic business information (EIN, address, etc.)
- Information on your revenue
Apply During Business Hours
Most quick lenders can approve your line of credit on the same day, but this is typically contingent on applying during standard business hours.
Start Small, Grow Your Credit
Your initial credit line may be smaller than you desire. By using it responsibly, you can demonstrate reliability to the lender, who will often increase your credit limit in a short period.
Gaining a Competitive Edge Through Financial Agility
Securing rapid access to capital is no longer just a convenience; it is a fundamental component of modern business strategy. A quick-approval line of credit empowers entrepreneurs to operate with agility. This flexibility allows them to turn unforeseen opportunities into tangible growth and effectively navigate unpredictable cash flow challenges. This financial tool bridges the critical gap between opportunity and execution, which traditional lending models often fail to address in a timely manner.
Proactively establishing a line of credit when your business is financially healthy is a hallmark of strategic foresight. This approach ensures that when a time-sensitive opportunity arises—from securing bulk inventory discounts to scaling a successful marketing campaign—the necessary capital is immediately at your disposal. In a competitive marketplace, the ability to act decisively is what separates industry leaders from their slower-moving counterparts.
Frequently Asked Questions About Fast Business Funding
What is the primary difference between a business loan and a line of credit?
A business loan provides a lump sum of capital that is paid back in fixed installments over a set period. A line of credit, conversely, is a revolving credit account that allows you to draw funds as needed up to a certain limit and only pay interest on the amount you use.
Will applying for a quick line of credit impact my personal credit score?
The impact depends on the lender and the type of credit line. Some lenders perform a “soft pull” during the initial application, which does not affect your credit score. A “hard pull” may be conducted upon final approval, which can have a minor, temporary impact. Always clarify the lender’s credit check process beforehand.
Are quick-approval credit lines more expensive than traditional bank loans?
Interest rates on quick-approval lines of credit can sometimes be higher than those from traditional banks to compensate for the increased speed and convenience. However, the cost must be weighed against the potential return on investment from seizing a time-sensitive opportunity that a slower bank loan would cause you to miss.
What are the typical requirements for a quick-approval business credit line?
While requirements vary, most online lenders prioritize recent business performance over long-term history. Applicants are typically asked to provide:
- Several months of recent bank statements.
- Basic business information (EIN, address, etc.).
- Proof of consistent monthly revenue.

